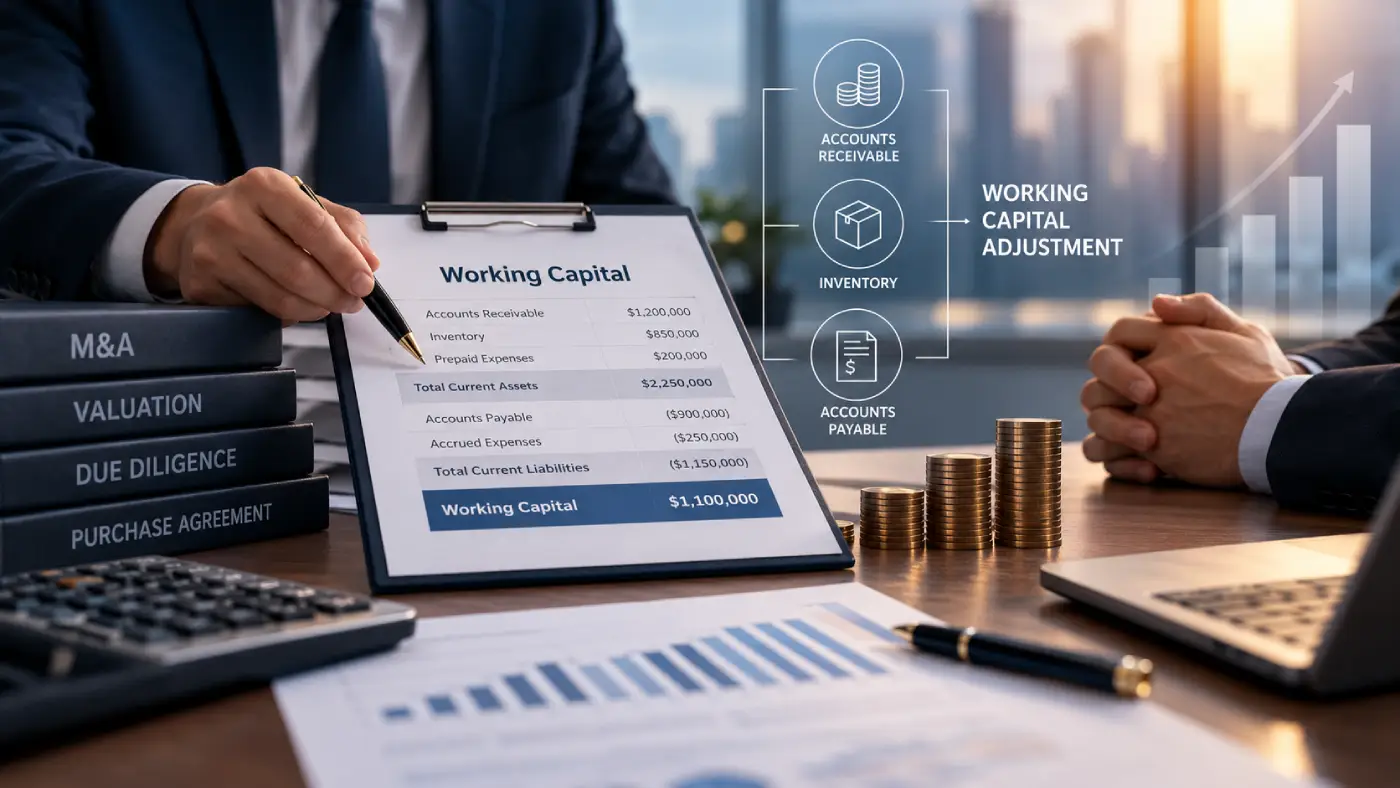
A buyer may agree to pay $10 million for a company, but that does not always mean the seller receives exactly $10 million. Several figures still need to be settled as the transaction moves toward closing. Working capital is one of them.
A working capital adjustment compares the amount a business is expected to have available for normal operations with what it actually has at closing. The difference can raise or lower the seller's final proceeds.
For business owners preparing for a sale, understanding this calculation early matters. It can help explain why the number written into an offer and the amount received at the end of the deal are not always identical.
Your Headline Sale Price May Not Be Your Final Number
When a buyer takes ownership, the company still needs to function the next morning. Customers need to be served, inventory may need replacing, and supplier bills still have to be paid.
That is where working capital in M&A becomes important. Buyers generally expect a company to come with a normal level of operating current assets and liabilities rather than receiving a business that immediately needs extra funding.
A working capital adjustment in M&A provides a way to measure that position. The parties establish an expected level and later compare it with the company's actual position at closing. The difference may become an M&A purchase price adjustment. For a seller, that means the headline valuation should never be viewed in isolation from the financial terms surrounding it.
The Working Capital Peg Sets the Starting Point
Buyers and sellers need an agreed target to measure whether the business has enough working capital at closing. This target, known as the working capital peg, is often based on the company's normal operating needs.
Past monthly balances can help set that number, but they should be viewed in context. Recent growth, unusual transactions, seasonal changes, or new supplier terms may mean that a simple historical average does not give an accurate picture.
Sellers working with a capital advisory investment banking team can review the figures and assumptions before agreeing to the target. Even a small change in the benchmark can affect the amount the seller ultimately receives.
Not Every Current Asset or Liability Makes the Cut
Working capital may sound like a simple current-assets-minus-current-liabilities calculation, but M&A agreements are usually more specific about which accounts count.
Accounts Receivable
Customer invoices that have not yet been paid are often included. Their quality matters, though. A recent invoice from a reliable customer is different from a balance that has been overdue for several months. The parties may need to agree on bad-debt reserves and how older receivables will be treated.
Inventory
Inventory needed to keep the company operating is another common part of the calculation. The question becomes more complicated when some stock is old, damaged, slow-moving, or unlikely to sell. Inventory reserves and valuation methods should be clear before the closing calculation begins.
Accounts Payable and Accrued Expenses
Bills owed to suppliers and expenses the business has already incurred can change the working capital figure. Timing matters as well. If payments that are normally made on time are pushed back until after closing, the numbers may not reflect the way the company usually operates.
Other balances, such as prepaid costs, customer deposits, and deferred revenue, may need to be reviewed separately. Cash and debt are also commonly handled outside the working capital calculation.
The purchase agreement should spell out how each of these accounts will be treated. That way, both sides are working from the same figures when calculating the net working capital adjustment.
See What a $200,000 Shortfall Does to the Deal
Consider a business with a $10 million agreed sale price and a $1.2 million working capital target. If the company has only $1 million in qualifying working capital at closing, there is a $200,000 shortfall.
With a dollar-for-dollar working capital adjustment, that shortfall could reduce the seller's proceeds to $9.8 million. On the other hand, if closing working capital reaches $1.4 million, the seller could receive an extra $200,000 when the agreement allows an upward adjustment.
This example shows why a purchase price adjustment needs attention before signing. Even a modest difference in working capital can have a noticeable effect on the amount the seller ultimately receives.
A Twelve-Month Average Does Not Always Tell the Full Story
A twelve-month average can provide a useful starting point, but it may not always reflect how the business operates today. If sales have grown quickly, the company may now need more inventory or carry higher receivable balances than it did earlier in the year.
Unusual activity can also shift the numbers. An early customer payment, a delayed supplier invoice, or extra inventory purchased for a large order may make one month stand out from the rest.
Looking at what caused these changes gives buyers and sellers a more accurate view of normal working capital. This can help them avoid relying on an average that no longer matches the company's current needs.
Seasonal Swings Can Move the Target
The month a deal closes can matter more than it first appears. A company's inventory, receivables, and unpaid bills may look quite different at various points in the year, even when the business is running normally.
A retailer, for example, may stock up before the holiday rush, while a landscaping company may carry more receivables during its busiest months. Manufacturers may also purchase extra materials ahead of a period of higher demand.
These regular shifts should be considered when setting the working capital peg. Without that context, a normal seasonal rise or drop could change the final adjustment and give an inaccurate picture of the business.
Watch What Happens to Working Capital Before Closing
Business operations should stay as consistent as possible while the sale moves toward closing. Sudden changes in billing, collections, purchases, or payments can make the closing figures look very different from the company's usual pattern.
For example, collecting invoices early can reduce receivables, while delaying supplier payments may increase accounts payable. Cutting inventory purchases can also leave the business with less stock than it normally needs. Buyers may notice these shifts when they compare recent figures with past months.
Working with a middle market financial advisory team can help sellers review these changes and see how they may affect the net working capital adjustment. The aim is to reach closing with figures that fairly reflect the company's normal operations.
The Final Calculation May Come After the Deal Closes
Closing day does not always provide the final numbers. Some invoices, expenses, or other balances may still need to be recorded, so the deal may move forward using an estimated working capital adjustment.
Once the books are updated, the buyer can calculate the actual working capital as of the closing date. The seller is usually given a set period to review the figures and question anything that does not match the agreed terms.
If the final amount is different from the estimate, a true-up settles the difference. The seller may receive more money or return part of the payment, depending on the result and the terms of the deal.
Small Accounting Differences Can Turn Into Expensive Disputes
A disagreement can start with something as small as one account. Buyers and sellers may value an old receivable differently or disagree over how certain inventory should be treated.
Accrued expenses, customer deposits, unpaid bills, and closing-date transactions can create similar questions. Problems may also arise when one side treats an item as normal working capital while the other considers it debt.
Several small differences can quickly add up and affect the M&A purchase price adjustment. Clear definitions and consistent accounting rules can help both sides avoid costly disputes after closing.
Protect Your Sale Proceeds Before Signing
Working capital deserves attention long before the closing papers are ready. Reviewing monthly figures early can uncover old receivables, excess or slow-moving inventory, unusual expense accruals, and changes in supplier payment terms. Finding these issues ahead of time gives the seller more room to understand what is affecting the numbers and correct recordkeeping problems where needed.
It is equally important to know which accounts will be part of the final calculation. Buyers and sellers should agree on what is included, what is left out, and which accounting methods will be followed. Comparing these terms with the company's past accounting practices can also reveal differences that might otherwise become a point of disagreement near closing.
Sellers can also test a few possible outcomes before signing. For example, calculate the expected proceeds if working capital finishes $100,000 below the target, meets it exactly, or ends $100,000 above it. Seeing those figures in dollars makes it much easier to understand how the adjustment could affect the money received from the sale.
Know the Number Before You Reach Closing
A company's valuation may get most of the attention during a sale, but the final amount received depends on more than the headline price.
A working capital adjustment in M&A can move real money between buyer and seller. Understanding the target, checking what is included, accounting for seasonal changes, and reviewing closing balances early can make the outcome much easier to anticipate.
A well-defined working capital adjustment will not guarantee that the final number matches the original sale price. It does, however, give both sides a clearer way to determine what should be paid when the business changes hands.
FAQs
1. Can working capital increase the final sale price?
It can. If the business has more working capital than the agreed target at closing, the seller may receive additional money. Whether that happens depends on how the adjustment is written into the deal.
2. What happens when working capital is below the target?
The difference may come out of the seller's proceeds. For example, a $50,000 shortfall could mean a $50,000 reduction if the agreement uses a dollar-for-dollar adjustment.
3. How is the working capital target usually determined?
There is no single number that works for every business. Buyers and sellers often look at past monthly figures along with seasonal patterns, recent growth, and any unusual activity that may have affected the company's normal working capital needs.
4. Is cash included in working capital for an M&A deal?
Cash is often excluded when a transaction is structured on a cash-free, debt-free basis. The purchase agreement should state exactly which accounts are included.
5. When is the working capital true-up completed?
It usually occurs after closing once the final closing-date balances are available. The agreement normally sets deadlines for preparing, reviewing, and disputing the calculation.